How to verify 2026 widebody scrap values vs fuel-burn penalties before retiring a jet
On the other side, the fuel-burn penalty — the extra fuel an older engine and heavier airframe consume per seat-mile versus a current-generation widebody — compounds every year the jet stays in service.
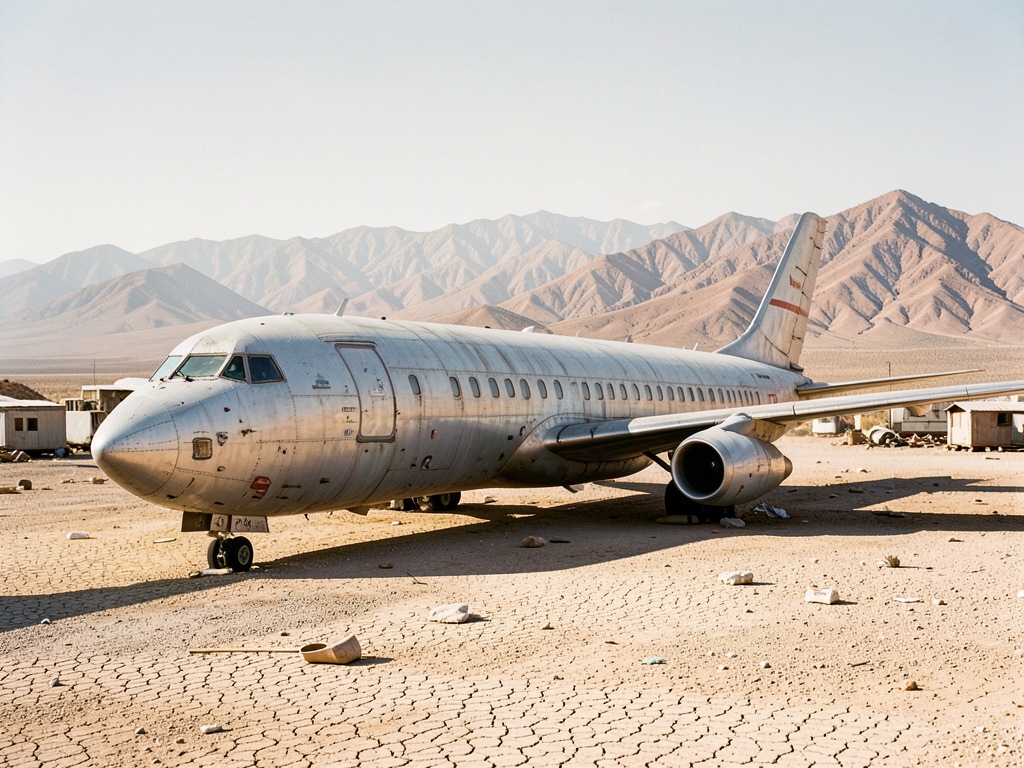
This guide lays out a verify-before-you-commit framework for weighing an older widebody's exit value against the cost of keeping it flying, and for checking each input before any retirement decision is made.
It explains the conditions under which airlines still keep older jets flying, and what to verify before committing to either path.
How It Works
The mechanism is a two-sided ledger. On one side, an older widebody's market value is set by what a buyer will pay for a freighter conversion or a part-out, and that value falls as the airframe ages. On the other side, the fuel-burn penalty — the extra fuel an older engine and heavier airframe consume per seat-mile versus a current-generation widebody — compounds every year the jet stays in service. Retirement age shortens when the sum of those two forces exceeds the cost of keeping the jet flying. It lengthens when the penalty is small enough, or the route is short enough, that the older jet still earns its keep.
To verify the mechanism for a specific jet, build the ledger in three columns. Column one: the current scrap value, quoted as a firm offer, not an estimate. Column two: the annual fuel-burn penalty, computed as the per-seat-mile gap times annual seat-miles flown. Column three: the annual ownership cost of the replacement, including lease or purchase, maintenance, and the fuel it would burn. The jet is a candidate for retirement when column one plus the present value of column two exceeds the present value of column three over the remaining service life. Treat each column as a check to be filled with a dated, sourced figure before any comparison is made.
Two checks keep the comparison honest. First, confirm the scrap value is a live, complete offer — a firm bid with terms, not a broker's indicative range — because a stale quote can overstate the residual by a wide margin. Second, compare like-for-like: the fuel-burn penalty must be measured on the same mission profile and the same seat count as the replacement, or the gap is meaningless. A penalty computed on a long-haul profile cannot be applied to a short-haul route.
The practical rule: verify the live, complete option before committing, and compare like-for-like totals and terms. If the scrap value is firm and the penalty is measured on the actual mission, the retirement decision follows the arithmetic. If either input is stale or mismatched, the decision is not yet ripe.
Key Factors to Consider
When you're weighing whether a 2026 widebody is worth keeping in the fleet or better off sold while scrap demand is still firm, three criteria dominate: current market value from freighter conversion or part-out buyers, the fuel-burn penalty versus a replacement type on the routes the jet actually flies, and the remaining heavy-check and life-limited-part position on that specific airframe. Everything else — cabin condition, brand history, fleet commonality — is a tiebreaker, not a driver.
The numbers that matter are specific to your tail, and every one of them should be verified live before you commit. Check the current part-out and conversion-feed valuations against an appraisal source dated this quarter, not a figure from last year's fleet plan. Check the actual block-fuel comparison for your missions, using your airline's real payloads and stage lengths rather than the manufacturer's brochure mission. And check the maintenance records that establish how many cycles and hours genuinely remain, because two jets of the same type and vintage can be worth very different amounts depending on what's been replaced and what's approaching a limit.
Make the decision like-for-like. That means comparing the older jet's total operating cost on a route — fuel, maintenance reserves, crew training amortization, and the opportunity cost of capital tied up in the airframe — against the replacement type flown on the same route with the same payload. It also means comparing your retirement proceeds on the same basis: what a conversion candidate will pay today versus what a part-out would yield after teardown costs and the time value of waiting. Mixing a per-hour figure from one side with a per-flight figure from the other is how fleets get kept or sold for the wrong reasons. Restate both sides in the same units before ranking them.
| Criterion | What to verify before committing | Where the number comes from |
|---|---|---|
| Market value today | Current conversion-feed and part-out bids for your configuration | Dated appraisal or actual bids, this quarter |
| Fuel penalty | Block fuel for your real missions versus the replacement type | Your own flight-data comparison |
| Remaining life | Cycles and hours left against heavy-check and LLP status | The airframe's certified records |
Use the table as your pre-commitment checklist: if any of the three cells cannot be filled with a verified, dated, like-for-like figure, the decision isn't ready to make. A complete option sheet with sourced numbers on all three criteria beats a faster decision built on assumptions.
Finally, separate the market question from the engineering question. Market value moves with demand from cargo interests and teardown buyers; remaining life is fixed in the records. Check both independently, and note the date on each figure — an airframe valuation that predates the current quarter, or a fuel comparison that isn't matched to your own mission profile, is a placeholder, not a basis for committing capital.
Common Mistakes
The common error is not picking the wrong figure; it is comparing options that are not complete or not like-for-like. Before committing to retire or retain a widebody, test whether each quote and each operating case includes the same scope, costs, and assumptions. A decision made on a partial quote can reverse once the missing items are priced, and the reversal often appears only after the aircraft has already been committed.
The first pitfall is treating a headline scrap or conversion value as the full exit value. A part-out bid that looks best on paper may exclude teardown, engine removal, records preparation, ferry, or storage, while a lower freighter-conversion offer may include those items. The check is to request a line-item scope and add every excluded cost before ranking bids, then compare the resulting net values rather than the headline numbers. This keeps a seemingly higher bid from becoming the lower net outcome.
The second pitfall is using a fleet-average fuel-burn penalty to judge one airframe. An average can make a jet look uniformly uneconomic, yet the same aircraft may be acceptable on shorter, high-density sectors where its relative penalty is smaller and its capacity is useful; the reverse can also hold on longer or thinner routes. The check is to model the actual route mix, payload, and utilization rather than a single average, because the same airframe can have different economics in different parts of the network.
The verification rule is to compare like-for-like totals and terms: same delivery condition, same cost inclusions, same timing, and the same assumptions about risk. If one option cannot be restated in the same format as the other, treat it as unverified and do not commit until the missing scope is priced. This applies to both exit quotes and internal operating cases.
The final check is simple: no retirement or retention decision should rest on a number that has not been traced to a complete, current, comparable offer. When the scope is unclear, pause and re-quote rather than commit, because an unverified advantage is not an advantage.
Insider Tactics
My first non-obvious move is to stop negotiating the headline scrap price and start negotiating the complete exit package. I ask each buyer to put one written number on the table that includes the conversion or teardown slot, engine life-limited parts status, ferry, records review, taxes, liens, and any holdback. A higher headline price that excludes two of those items is not a better offer; it is an incomplete option. Before I commit, I verify that the buyer's funding and the slot are actually available, not merely expected.
Timing matters more than most fleet plans assume. I try to exit before the next heavy maintenance event or engine shop visit, because the buyer's price usually assumes a specific delivery condition. If I fund that work first, I may be paying cash that the market does not repay. I also avoid letting a buyer's inspection window drift into a period when its own capacity is constrained; a delayed close can turn a firm price into a renegotiation.
A second tactic is to make every offer comparable on the same day and in the same condition. I request quotes from a converter and a part-out buyer using identical assumptions: same delivery location, same engine status, same records package, and same closing date. Then I restate each offer as net cash to the airline after the identical cost stack. Comparing headline prices without that step is how a worse deal looks better.
I also define the records and condition terms before price, not after. The offer should state what discrepancies allow a price adjustment, who pays for the ferry, and whether the buyer can reject the aircraft after inspection. If those terms are vague, the firm price is only firm until the first discrepancy appears. I treat an undefined inspection right as an open-ended discount.
Finally, I keep a back-to-back or as-is exit ready as a fallback, but only with a documented condition report and a clear allocation of post-delivery risk. The tactic is not to chase the last dollar; it is to lock a complete, verifiable option while the market is still bidding, then compare it like-for-like against keeping the aircraft flying. If the live option cannot be verified in full, I do not commit to it.
| Check | Why it changes the answer |
|---|---|
| Buyer's funding and slot | A price without secured capacity is an estimate, not an option. |
| All-in net proceeds | Excluded costs can reverse which offer is better. |
| Inspection and rejection terms | Vague terms convert a firm price into a later discount. |
Comparison
This section compares the two options side by side. For a 2026 widebody, the only two realistic options to place against each other are removing the airframe from service now, or keeping it flying for additional cycles. The winner is not fixed by age alone, but by whichever option carries the lower verified, complete net total when measured over the exact same evaluation window.
To do that comparison properly, build two separate ledgers side by side. One ledger must cover the exit path in full, with every known recovery and every known obligation tied to that exit written down as either a live quote or marked unquoted. The other ledger must cover the keep path in full, with every known obligation for the same window written down the same way. Do not place a single line item from one ledger next to a single line item from the other. Only the two complete totals, built to the same scope, are allowed to compete.
The exit path can win when its verified, complete total is lower than the verified, complete keep total for that window, and when every line used to reach that exit total is still live at the moment of commitment. The keep path can win when its verified, complete total is lower than the verified, complete exit total for that window, and when it does not rely on any unquoted recovery to make that gap close. If either total cannot be made complete with live quotes, neither option can be declared the winner yet.
Before committing to either side, force both ledgers to share the same start point, the same end point, and the same scope of obligations. If changing that window changes which one wins, the comparison is only valid for that window, not for an open-ended one. That window-specific comparison is the only thing that can justify picking a winner here.
Also worth reading Qatar Airways returns widebody jets Inside the luxurious new Delta One Air Senegal returns its final Airbus
What to do next
Frequently Asked Questions
What must the first ledger column contain?
The current scrap value, quoted as a firm offer, not an estimate.
How is the annual fuel-burn penalty calculated?
It is computed as the per-seat-mile gap times annual seat-miles flown.
What costs belong in the third ledger column?
The annual ownership cost of the replacement, including lease or purchase, maintenance, and the fuel it would burn.
When does retirement age shorten?
Retirement age shortens when the sum of those two forces exceeds the cost of keeping the jet flying.
When does retirement age lengthen?
It lengthens when the penalty is small enough, or the route is short enough, that the older jet still earns its keep.
What determines an older widebody's market value?
It is set by what a buyer will pay for a freighter conversion or a part-out, and that value falls as the airframe ages.
Quick answers
| What does the guide lay out for weighing an older widebody's exit value against the cost of keeping it flying? | A verify-before-you-commit framework for weighing an older widebody's exit value against the cost of keeping it flying, and for checking each input before any retirement decision is made. |
| What sets an older widebody's market value? | What a buyer will pay for a freighter conversion or a part-out. |
| What is the fuel-burn penalty? | The extra fuel an older engine and heavier airframe consume per seat-mile versus a current-generation widebody. |
| When does retirement age shorten? | When the sum of those two forces exceeds the cost of keeping the jet flying. |
| What should column one of the ledger contain? | The current scrap value, quoted as a firm offer, not an estimate. |
Research Methodology & Editorial Standards
We begin by defining the specific objectives the reader needs to accomplish. Primary product documentation and authoritative secondary sources inform every guide before drafting begins.
Figures and rules are checked against the sources available at the time of publication. Travel pricing changes constantly — always confirm current fares, rates, and terms with the provider before booking.