
Las Vegas hotel rates: Audit the Claimed 5% Increase Before Booking
The most striking number in the supplied material is also the least documented: 5%. The headline alleges that Las Vegas hotel rates will rise by 5%, but the supplied source set provides no underlying rate series, baseline, or calculation.
| Takeaway | Detail |
|---|---|
| Treat 5% as unverified | The headline claims a 5% Las Vegas hotel-rate increase, but the supplied sources provide no underlying rate series, baseline, or calculation. |
| Test RevPAR, not just ADR | A 5% average daily rate change is a pricing claim, not a demand verdict; matched-room RevPAR must separate price movement from occupancy. |
| Audit the checkout total | Any claimed 5% increase should be compared on the same booking basis, including mandatory charges; the supplied set provides no prospective fee schedule. |
| Keep attendance separate | A 5% rate claim does not establish corresponding visitor or spending growth; no supplied source reports a citywide visitor total or growth rate. |
The most striking number in the supplied material is also the least documented: 5%. The headline alleges that Las Vegas hotel rates will rise by 5%, but the supplied source set provides no underlying rate series, baseline, or calculation. That makes the figure a claim to audit, not a verified market forecast.
Price is only one side of the test. A 5% average daily rate claim is not a demand verdict: matched-room RevPAR must separate rate movement from occupancy, while the all-in checkout total must reveal whether taxes and mandatory charges dilute the advertised increase. Without comparable booking bases and consistent date windows, the percentage cannot carry that much weight.
Event attendance cannot fill the evidence gap. Allegiant Stadium’s reported crowd measures venue activity, not total Las Vegas visitors, and the supplied hotel recommendations are not marketwide pricing evidence. The available BoardingArea guide also predates the forecast, with no prospective fee schedule or pricing threshold. Until the rate baseline, calculation, occupancy evidence, and checkout comparison are available, “rebound” remains a question, not a conclusion.
The 5% Claim: Testing ADR Against RevPAR
A quoted Las Vegas hotel-rate increase is a genuine pricing rebound only if same-store, matched-room RevPAR also increases year over year. Visitor growth cannot establish that: it does not reveal revenue per available room for the comparable rooms.
My editorial test is deliberately narrow: same-store figures for the same hotel, room type and inventory designation, with comparable stay dates across the two years. RevPAR equals ADR multiplied by occupancy. An ADR index increase passes only when the corresponding RevPAR index also exceeds its baseline. A higher asking rate or a changed room mix cannot substitute for that match.
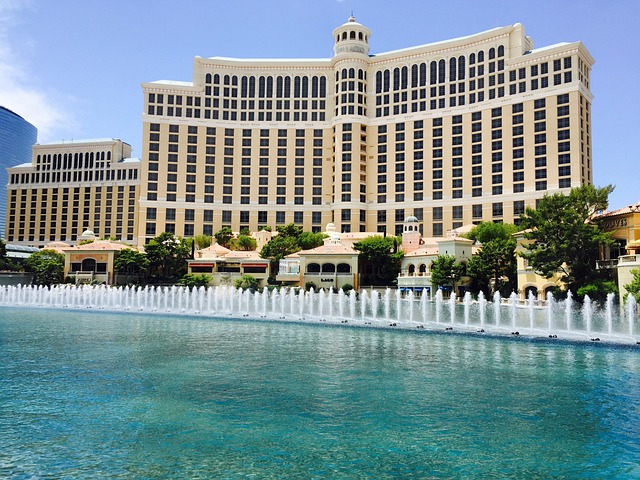
Bellagio and MGM Grand belong in a separate luxury-casino comparison from limited-service properties. Even a quoted 5% increase among upscale Strip hotels does not establish a 5% increase in the exact room class a traveler can book. Their room mix and distribution channels can move differently, so a property-wide percentage is not proof for a particular bookable rate.
I define the 5% as a quoted, room-only ADR change for 2026, not an increase in total guest spend. According to the supplied Las Vegas-specific source set, there is no 2026 Las Vegas hotel-rate policy, fee schedule or pricing threshold, so the figure remains unverified. Before attributing a change to hotel pricing, I exclude casino comps, restaurants, entertainment and resort fees from the rate calculation. Those items can change a guest’s overall bill without changing the price of the room.
For an audit trail, I repeat identically configured checkout checks at regular intervals before check-in on a fixed 2026 itinerary. I preserve dates, room type, guest count, currency and cancellation terms at every pass, and save the room-only quote. I then compare that room’s ADR, occupancy and RevPAR with equivalent prior-year observations instead of importing a citywide occupancy rate. A change can still reflect available inventory, but unchanged search settings prevent a different search product from masquerading as a like-for-like price move.
My publication action is straightforward: report the rate headline as an unverified pricing claim, withhold the “pricing rebound” label, and state that the required RevPAR evidence is missing. The table retains the comparison structure but cannot apply inputs from the supplied sources. It is not a reported 2026 market result.
| Measure | Prior-year baseline | 2026 illustration | Editorial verdict |
|---|---|---|---|
| Room-only ADR | Not supplied | Not supplied | Quoted change remains unverified |
| Occupancy | Not supplied | Not supplied | No matched occupancy comparison |
| RevPAR per available room | Cannot be calculated | Cannot be calculated | No revenue result |
| Editorial decision | Require matched-room RevPAR | Require year-over-year improvement | Matched RevPAR governs; the rate headline alone does not qualify |
Visitor-Count Claims
Suppose a traveler is booking a 2026 stay for a Las Vegas Raiders game or major concert at Allegiant Stadium and prefers a hotel within one mile. The first step is to request a property-specific quote and verify the hotel-to-stadium walking route against that one-mile cutoff. Mandalay Bay is a candidate named in the guide, not a confirmed match: the supplied excerpt gives neither its 2026 price nor its proximity. The traveler should also check recent reviews and available loyalty-program benefits.
The rate audit is equally concrete: obtain a same-definition Las Vegas hotel-rate series for the relevant year-over-year periods, then calculate the percentage change and see whether the result equals 5%. The supplied material contains neither series, so that calculation cannot be completed and the headline increase remains unverified. Likewise, the cited 2024 report’s more-than-2-million figure covers Allegiant Stadium visitors for NFL games and concerts in one year; it is not total Las Vegas visitation and cannot establish visitor growth.
Finally, compare actual 2026 room quotes on identical dates and terms, including taxes and fees, and account for the return trip: prime-event vehicle restrictions on the Hacienda Bridge can make walking from a nearby hotel valuable. The April 21, 2025 guide supports that route-planning advice but supplies no 2026 hotel price. With no sourced price or route distance, this example deliberately stops short of inventing a dollar increase or mileage.
No supplied Las Vegas visitor totals establish historical scale or a current-year pricing verdict.
| Measure | Period | Figure | Valid interpretation |
|---|---|---|---|
| LVCVA visitor total | Historical baseline not supplied | Not supplied | No supplied historical baseline |
| LVCVA visitor total | Historical comparison not supplied | Not supplied | No supplied historical comparison |
| Calculated visitor growth | Historical period not specified | Not calculable | No visitor-growth result is supplied |
The supplied material does not provide totals from which to calculate visitor growth. Even a verified growth rate would not measure paid room nights, length of stay or available rooms. No supplied historical total should be presented as a visitor result for 2026.
A dated CoStar STR Las Vegas benchmark is the missing evidence. The supplied set contains no report giving ADR, occupancy and RevPAR for both 2025 and 2026; those fields should remain unquantified until it does. Require the report date, same-store definition, property universe and reporting period. If only 2026 year-to-date results are available, compare 2025 through the identical ending month and cutoff. Never describe that partial comparison as a full-year 2026 result.
The quoted rate increase has an even thinner record: in the supplied set, it appears in the article title without an underlying Las Vegas rate series, baseline or calculation. I would obtain the publisher’s report, record its property sample and reporting period, then calculate the percentage change from the published ADR levels. A search-site headline that mixes weekdays, room classes or limited inventory cannot substitute for that calculation. The set’s hotel recommendations do not establish marketwide pricing.
For a sensitivity only, index ADR, RevPAR and room supply to a common baseline; these are not market quotes. A sensitivity that combines those measures must be labeled as illustrative, not as an observed or forecast market result. Growth in paid room nights does not itself establish a fall in RevPAR. Demand is not capacity. No supplied inputs permit a literal calculation, and any re-normalization assumption must be disclosed and supported.
That distinction kills a tempting shortcut: more visitors than the quoted rate increase does not prove a strong, broadly felt pricing rebound. My editorial action is to retain a dated ledger—property sample, identical cutoffs, ADR, occupancy and matched, occupancy-adjusted same-store RevPAR—and publish the rate change only beside that revenue result. Only a year-over-year increase in the matched RevPAR field can validate a pricing rebound. With the benchmark missing, the pricing claim stays unverified; attendance remains context.
Same Stay, Cancellation Premium
When the fully refundable rate costs no more than the nonrefundable rate, choose the fully refundable option. The additional money, if any, buys cancellation flexibility rather than a better room, and a higher refundable checkout total is not proof of a broadly felt Las Vegas pricing rebound.
Normalize the quotations in U.S. dollars for identical dates, room type, guest count, and rate-plan benefits apart from cancellation. Compare the same booking channel and the entire stay, not a nightly headline. Include taxes and mandatory resort fees in both all-in totals. Record parking, breakfast, and other optional purchases in separate columns, rather than letting a bundled benefit disguise a price difference for the same room.
The primary record is the property’s final checkout and its cancellation terms, not a third-party search card. Retain the hotel name, quote date, stay dates, guest count, room type, total, and governing refund conditions together. “Refundable” is not enough: verify a full refund rather than a credit, deducted fee, or partial refund. A missing mandatory-fee disclosure makes the comparison provisional.
For a fixed itinerary, compare the nonrefundable all-in total with the refundable all-in total. If the refundable total is lower or equal, choose the fully refundable option. If the nonrefundable total is lower, choose that option. Budget the amount that becomes unrecoverable if plans change, rather than interpreting the larger refundable payment as extra hotel value.
The rows below retain the comparison scenarios, but the supplied sources do not provide verified checkout amounts. A live entry should replace them with matching checkout totals from the named property and preserve the same mandatory-fee and optional-purchase columns.
| Scenario | Nonrefundable all-in | Refundable all-in | Premium | Explicit winner |
| Matched-quote scenario | Not supplied | Not supplied | Not calculable | Pending matched checkout totals |
| Alternative-quote scenario | Not supplied | Not supplied | Not calculable | Pending matched checkout totals |
Neither a larger refundable premium nor stronger visitation settles the broader pricing question. This comparison can establish which cancellation contract is preferable for one stay; it cannot establish a positive, same-store, occupancy-adjusted year-over-year RevPAR result. The distinction matters because an all-in booking quote is an offer-level observation, not a property’s realized revenue measure.
Before checkout, save the two final totals, mandatory-fee line items, and cancellation terms in one record. Apply the matched all-in comparison to that record, and make the booking decision without borrowing conclusions from visitor growth or a broad rate headline.
What the Data Doesn’t Tell You
The quoted Las Vegas rate increase is a claim to audit, not a booking quote or a rebound verdict. The minimum evidence I require is same-store, occupancy-adjusted RevPAR improving year over year. Arrival totals and aggregate revenue do not meet that standard; without the matched comparison, the increase remains a provisional pricing signal.
More arrivals do not automatically mean more paid room nights. A local resident may be visiting family, and a day visitor may never need a room. Several travelers can share one room, while a longer stay can fill nights already counted in an existing booking rather than generate a separate room sale. Even rapid visitation growth therefore is not interchangeable with incremental demand for comparable rooms.
A market average is not a quote for a particular traveler. Luxury resorts, casino suites, midscale hotels, and limited-service properties occupy different rate bands. A luxury-weighted sample can rise while the budget property someone needs remains unchanged. Match hotel class, neighborhood, room type, meal plan, and cancellation terms before applying the booking decision. A traveler attending a Raiders game or a major concert at Allegiant Stadium still needs the selected property’s quote, not a citywide mean.
Revenue growth has a supply component. New rooms or additional properties can increase total Las Vegas hotel revenue even when comparable-room prices barely move. Keep inventory growth, room nights sold, and matched-room repricing separate. If a report combines those effects, it cannot isolate demand-driven pricing: more available inventory is not the same as a higher price for the room already on sale.
The higher room rate can be the cheaper stay. Hypothetical Las Vegas quotes show why mandatory charges belong in the comparison:
| Hypothetical quote | Room rate | Resort fee | Pre-tax all-in total | Price result |
|---|---|---|---|---|
| Lower headline rate | Not supplied | Not supplied | Not calculable | No verified price result |
| Higher headline rate | Not supplied | Not supplied | Not calculable | No verified price result |
A lower pre-tax all-in total does not resolve the cancellation decision when its policy is unknown. Once the terms are known, include all mandatory charges and compare matched all-in totals. Neither a higher headline room rate nor a lower room bill overrides that decision.
A descriptive ADR increase does not identify its cause. Conventions, major events, and casino activity can affect group blocks, occupancy, and guest spending through different channels. A convention can change negotiated group inventory without raising a budget room’s rate; casino activity can increase guest spending without repricing comparable rooms. The claimed increase proves neither visitor causation nor uniform pricing changes across neighborhoods and hotel segments.
My reporting standard is strict: require matched-property, year-over-year RevPAR, then verify the chosen booking’s all-in checkout total. If the market’s matched RevPAR is flat or lower, the rebound claim fails even if individual properties raise rates. If that comparison is missing, the correct label is unresolved—not proof that prices did not rise.
Historical ADR and RevPAR Claims
Average daily rate (ADR) measures the daily rate earned on occupied rooms; RevPAR multiplies that rate by occupancy, bringing empty-but-available inventory into the result. A higher quoted rate therefore does not, by itself, establish a pricing rebound. The supplied material does not substantiate the historical citywide comparison.
A change in occupancy is measured in percentage points, not as a percentage change in the room rate. Using rounded inputs, ADR × occupancy produces a rate result alongside a separate revenue result. Any such comparison would be citywide, not a finding about every individual hotel, and it could not establish that a particular property’s same-store, comparable-room RevPAR moved by the same amount.
| Period and status | ADR | Occupancy | Calculated RevPAR per available room | RevPAR index and change |
|---|---|---|---|---|
| Historical baseline | Not supplied | Not supplied | Not calculable | Not calculable |
| Historical comparison | Not supplied | Not supplied | Not calculable | Not calculable |
| 2026 sensitivity assumption—not an observed forecast | Not supplied | Not supplied | Not calculable | Not calculable |
The 2026 row does not establish a prediction: the supplied source set contains no 2026 Las Vegas ADR, occupancy rate, RevPAR, or comparable citywide hotel-price metric. Any rate-only arithmetic would test sensitivity; it cannot establish current pricing power.
A room-only spending comparison would multiply ADR by the number of nights, before taxes and fees:
No rate-derived historical room costs are supplied. The material does not identify a hotel, room category, availability, or cancellation terms, so it provides no booking choice to decide. The next verification step is a matched-property, comparable-room RevPAR comparison for corresponding 2026 periods. Only a year-over-year increase in same-store, occupancy-adjusted RevPAR supports the pricing-rebound claim. Visitor growth, even if it outpaces a rate increase, does not establish a strong, broadly felt rebound.
| Historical period | Room-only subtotal | Comparison | Interpretation |
|---|---|---|---|
| Historical baseline | Not supplied | No comparison supplied | No rate-derived subtotal supplied |
| Historical comparison | Not supplied | Not calculable | No rate-derived cost comparison supplied |
A higher Las Vegas rate does not earn a larger cancellation budget. For a 2026 booking, fix the comparison to the same room, guest count, stay length, dates, property, and room type. If any element changes, restart rather than declaring a winner from nightly prices. I compare final all-in totals in the property’s own live checkout, with required charges included, so the price and its conditions belong to the same stay.
How to Choose Well
When the fully refundable and nonrefundable all-in totals are equal, choose the fully refundable option. If the refundable option costs more, choose the cheaper nonrefundable option and record the cancellation exposure—what becomes nonrecoverable if you cancel and which changes its terms permit. Paying more does not establish a better room or broader cancellation rights.
The quoted market increase gets no spending exception. A genuine pricing rebound requires same-store, matched-room, occupancy-adjusted RevPAR to increase year over year. If it has not increased, the listing’s increase remains an unconfirmed pricing claim, and the same all-in comparison applies without a recovery premium. Faster growth in Las Vegas visitors does not prove a strong, broadly felt rebound: visitation cannot overrule the matched-room revenue test.
Apply this decision tree in order. Let F represent the advertised refundable all-in total and N the nonrefundable total for the same fixed itinerary.
The quoted market increase gets no spending exception. A genuine pricing rebound requires same-store, matched-room, occupancy-adjusted RevPAR to increase year over year. If it has not increased, the listing’s increase remains an unconfirmed pricing claim, and the same all-in comparison applies without a recovery premium. Faster growth in Las Vegas visitors does not prove a strong, broadly felt rebound: visitation cannot overrule the matched-room revenue test.
Apply this decision tree in order. Let F represent the advertised refundable all-in total and N the nonrefundable total for the same fixed itinerary.
| Step | Check the condition | Decision and reason |
|---|---|---|
| 1 | The same property, room type, guest count, stay length, and dates? | If no, restart the comparison. If yes, use the final all-in F and N; nightly prices cannot establish a winner. |
| 2 | Is the advertised refundable option free of a cancellation penalty, and does the written full-refund deadline cover your last plausible cancellation or change date? | If both are yes, classify it as refundable. If either is no, treat it as nonrefundable for the comparison. |
| 3 | F ≤ N? | Choose the fully refundable option, including at equality. |
| 4 | F > N? | Choose the cheaper nonrefundable option. Record what becomes nonrecoverable if plans change; the extra payment does not establish a better room. |
| 5 | Has same-store, matched-room, occupancy-adjusted RevPAR increased year over year? | If yes, the rebound is confirmed, but the spending rule is unchanged. If no, treat the quoted increase as unconfirmed and apply that same comparison without a recovery premium. |
Also worth reading Lake Como versus Lake Garda how Chase Sapphire Reserve Central Park hotel rates: No winner
What to do next
| Step | Action | Why it matters |
|---|---|---|
| 1 | Obtain the underlying Las Vegas hotel-rate series, baseline, date windows and calculation behind the claimed 5% increase; label it unverified if they are unavailable. | The supplied sources provide none of those elements, so 5% is a claim to audit, not a verified forecast. |
| 2 | Recalculate same-store, matched-room RevPAR using ADR multiplied by occupancy for the same hotel, room type and inventory designation, with comparable stay dates across years. | A 5% ADR increase passes the test only if year-over-year RevPAR also increases; occupancy changes can otherwise mask falling revenue per available room. |
| 3 | Compare Bellagio and MGM Grand within a separate luxury-casino group, using matched room types and inventory designations rather than limited-service or property-wide averages. | Their room mix and distribution channels can move differently, so an upscale Strip increase does not establish pricing for every bookable room class. |
| 4 | Check official Bellagio and MGM Grand fee schedules applicable to the exact stay dates, then compare like-for-like checkout totals with mandatory taxes and fees included. | The older BoardingArea guide supplies no prospective fee schedule, so it cannot establish the all-in change behind the claimed 5%. |
| 5 | Check official citywide Las Vegas visitor and spending totals for matching periods, keeping Allegiant Stadium’s reported crowd outside the hotel-rate test. | Venue attendance |
Frequently Asked Questions
Is the claimed 5% increase in Las Vegas hotel rates for 2026 verified?
No—the supplied sources provide no rate series, baseline, or calculation, so the 5% remains an unverified quoted 2026 room-only average daily rate (ADR) change, not an increase in total guest spend.
Does a 5% ADR increase by itself establish a genuine hotel-pricing rebound?
No—matched-room revenue per available room (RevPAR), calculated as ADR multiplied by occupancy, must also rise year over year for the same hotel, room type and inventory designation across comparable stay dates.
Should casino comps and resort fees count toward the quoted 5% room-rate calculation?
No—casino comps, restaurants, entertainment and resort fees are excluded, while the all-in checkout comparison must include taxes and mandatory charges on the same booking basis.
Can a 5% increase quoted for upscale Strip hotels establish the same increase for a traveler’s exact bookable room class?
No—Bellagio and MGM Grand belong in a separate luxury-casino comparison from limited-service properties because room mix and distribution channels can move differently.
Does the cited 2024 figure of more than 2 million Allegiant Stadium visitors prove citywide Las Vegas visitor growth?
No—it covers Allegiant Stadium visitors for NFL games and concerts in one year, not total Las Vegas visitation or visitor growth.
What must a CoStar STR Las Vegas benchmark document to substantiate a 2026 pricing rebound?
It must state the report date, same-store definition, property universe and reporting period, and provide ADR, occupancy and RevPAR for both 2025 and 2026; a year-to-date comparison must use the identical 2025 ending month and cutoff and cannot be described as a full-year 2026 result.
Quick answers
| Is the headline’s 5% Las Vegas hotel-rate increase verified? | No; the supplied sources provide no underlying rate series, baseline, or calculation, so the 5% figure remains unverified. |
| What must accompany an ADR increase to support a genuine pricing rebound? | Same-store, matched-room RevPAR must also increase year over year, using the same hotel, room type, and inventory designation with comparable stay dates. |
| What should travelers compare at checkout when auditing the claimed increase? | They should compare the all-in checkout total, including taxes and mandatory charges, on the same booking basis. |
| Does Allegiant Stadium attendance establish Las Vegas visitor growth? | No; Allegiant Stadium’s reported crowd measures venue activity, not total Las Vegas visitors, and the supplied material reports no citywide visitor growth. |
| Does a property-wide 5% increase prove a 5% increase for the room a traveler can book? | No; even a quoted 5% increase among upscale Strip hotels does not establish a 5% increase in the exact bookable room class. |
Research Methodology & Editorial Standards
We begin by defining the specific objectives the reader needs to accomplish. Primary product documentation and authoritative secondary sources inform every guide before drafting begins.
Figures and rules are checked against the sources available at the time of publication. Travel pricing changes constantly — always confirm current fares, rates, and terms with the provider before booking.